المحتويات
مقال
Nvidia’s AI power play: what the market is really pricing in
December 12, 2025
مقال
Nvidia’s AI power play: what the market is really pricing in
December 12, 2025
مقال
Nvidia’s AI power play: what the market is really pricing in
December 12, 2025
According to analysts, Nvidia has become the gravitational centre of the AI economy, influencing everything from chip supply to geopolitics. Its latest quarter underscored the scale of that dominance, with revenue reaching $57 billion and data center sales rising 66% year-over-year. Yet the story surrounding the stock has now widened beyond earnings beats and supply shortages.
Regulators, global politics, and renewed competition for AI infrastructure contracts increasingly shape investor expectations alongside product cycles. Nvidia’s near-term outlook hinges on whether demand can stay ahead of tightening export rules and the surge in capital expenditure from rivals.
What’s driving Nvidia’s momentum?
A powerful wave of global AI spending continues to propel Nvidia’s growth. The company has described its cloud partners as “sold out”, signalling another year in which supply is likely to struggle to keep pace with demand. Market researchers anticipate that the AI chip industry will reach approximately $286 billion by 2026, up from $207 billion in 2025. That tight supply environment strengthens Nvidia’s pricing power and reinforces its status as the hardware gatekeeper for generative AI.
Geopolitics, rather than technology alone, is now adding new layers to the narrative. President Trump’s approval for Nvidia to export H200 chips to selected Chinese customers has reopened a revenue stream that had dwindled under earlier restrictions. The twist is a 25% revenue-sharing requirement with the U.S. government, far higher than the previous 15% fee applied to the weaker H20 accelerator. The compromise grants Nvidia partial access to a once-critical market, but only under terms that remind investors the regulatory backdrop is still shifting.
Why it matters
China once accounted for roughly a quarter of Nvidia’s revenue, so any pathway back into the region carries strategic weight. Analysts note that current financial forecasts assume almost no meaningful contribution from China, meaning H200 shipments could provide upside rather than simply filling a gap. The revenue-sharing fee, however, compresses margins and underlines how political clearance can come at a cost. It also fuels a legal debate about whether such arrangements effectively amount to export taxes.
Some fund managers view the mixed signals around China as part of a broader recalibration of the AI trade. Morgan Stanley recently raised its target to $250, arguing that fears of market-share erosion are overstated and that Nvidia remains the “AI hardware king”. That stance reflects a wider sentiment: the bottleneck for high-end AI compute still runs through Nvidia’s supply chain. Any sign of loosening in tight markets - even a partial one - can ripple through sector valuation models.
Impact on the tech market
The export decision triggered immediate interest from ByteDance and Alibaba, which reportedly want sizeable allocations of the newly approved H200 chips. Their enthusiasm highlights China’s hunger for higher-performance compute after months of relying on the much weaker H20. At the same time, Beijing’s caution about foreign chips and Nvidia’s limited H200 output inject uncertainty. Investors increasingly treat China as a volatile bonus opportunity layered on top of Nvidia’s core business, rather than a dependable growth pillar.
Meanwhile, Nvidia’s own technology roadmap keeps expanding its competitive moat. Analysts note that its upcoming Blackwell and Rubin chips sit at the centre of what management describes as “visibility to a half-trillion dollars” in future AI revenue.
The company has also rolled out location-verification software to curb chip smuggling - a move some industry reports suggest is a pre-emptive bid to stay ahead of regulators after reports of grey-market attempts to move $160 million worth of hardware into China. These tools may temper demand in some sensitive jurisdictions, but they strengthen Nvidia’s credibility as a compliant and proactive supplier.
The wider tech sector continues to be pulled into Nvidia’s orbit. Oracle’s sharp stock sell-off - down about 11% after reporting weaker revenue despite heavy AI spending - dragged Nvidia and other AI names lower on the day. According to analysts, the episode highlighted how closely investor sentiment is now tied to any signal about the AI capex cycle, especially from firms competing for the same infrastructure budgets. Market reactions show that while Nvidia may enjoy sector-leading fundamentals, it does not operate in isolation.
Expert outlook
Analysts remain overwhelmingly bullish despite regulatory twists and political noise. Across major platforms, average 12-month price targets cluster between $248 and $258, implying roughly 30–40% upside from recent levels. Evercore ISI and Cantor Fitzgerald see scope for the stock to move beyond $300 in 2026 if AI infrastructure spending holds its current pace. Their models depend on Nvidia maintaining its dominance in high-end accelerators, with free cash flow potentially exceeding $100 billion a year within two years.
Longer-term projections stretch into far more ambitious territory. Some multi-year scenarios imagine Nvidia approaching a $20 trillion market cap by 2030, depending on how aggressively the world scales AI computing. These views assume a future in which data centre expansion, autonomous systems, and edge AI create a continuous upgrade cycle rather than a rapid boom followed by stagnation. The biggest known unknown remains geopolitical stability: fresh export rules or supply-chain disruption could slow that cycle as effectively as any softening in end-user demand.
Key takeaway
Nvidia remains the indispensable engine of the AI boom, even as politics and export rules tighten around it. Strong demand, record earnings, and an unmatched product pipeline continue to outweigh mounting regulatory and competitive risks, according to reports. The partial, costly reopening of China adds an extra layer of optionality to the investment case, rather than simply returning to the old status quo. The next signals to watch will be Blackwell’s rollout, regulatory shifts in Washington and Beijing, and whether cloud providers remain capacity-constrained through 2026.
Nvidia technical insights
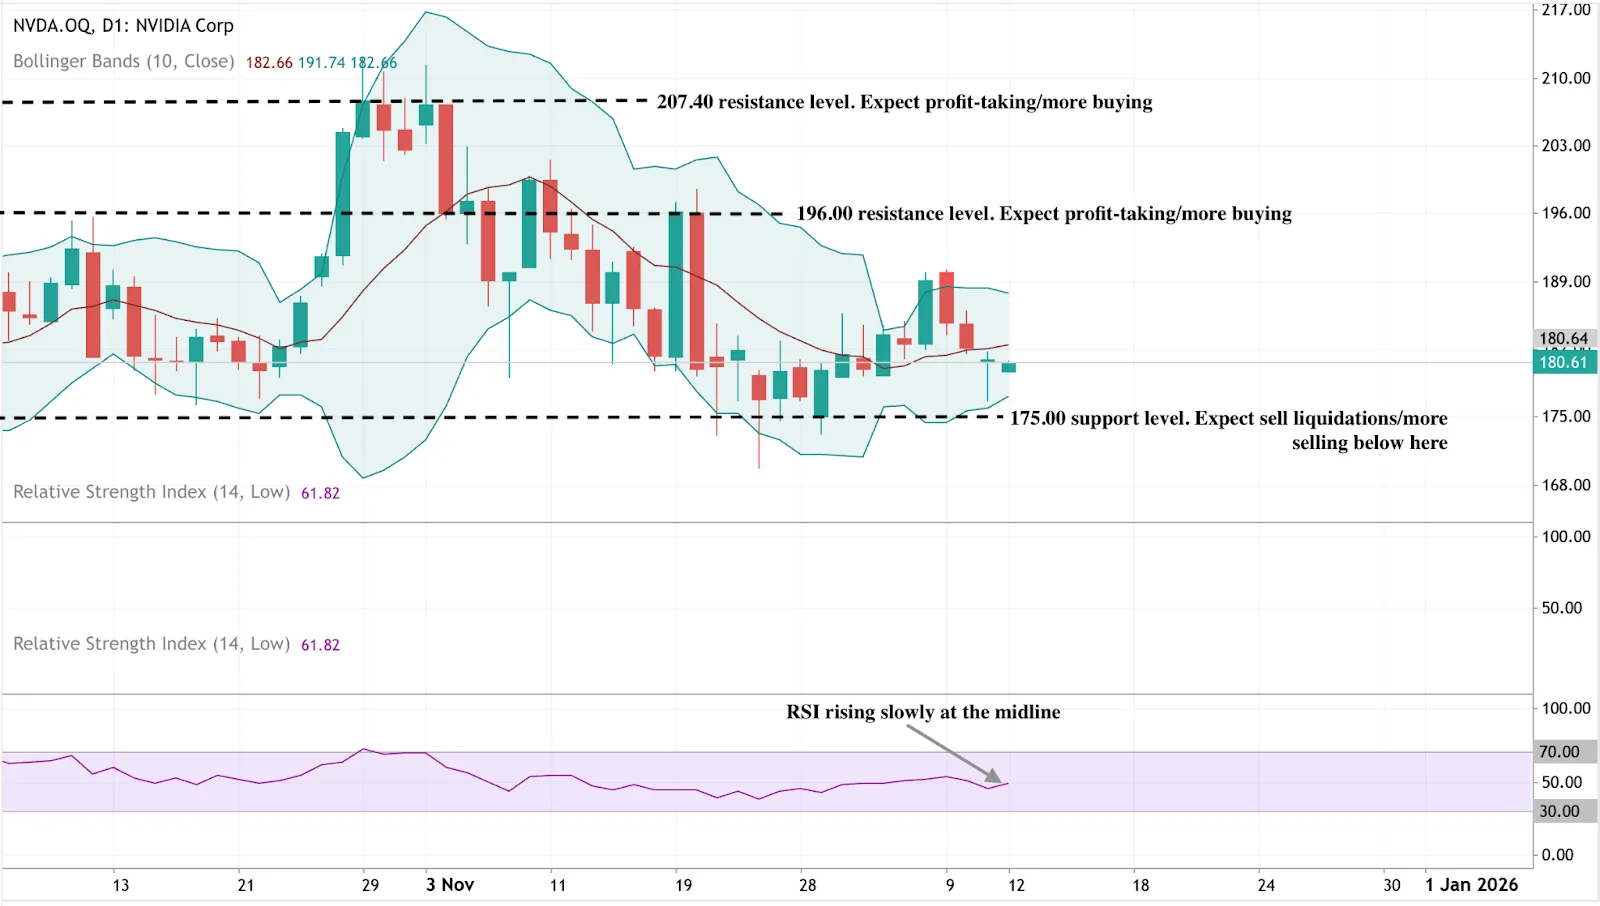
NVIDIA is stabilising above the $175 support level after a weeks-long pullback, with the Bollinger Bands beginning to narrow as price consolidates. The RSI is rising gradually from the midline, signalling a mild improvement in momentum, but not yet enough to confirm a bullish reversal.
Upside attempts face resistance at $196 and $207, where previous rallies have triggered profit-taking. A break below $175 would risk fresh liquidations, while sustained closes above $196 would be the first sign that buyers are regaining control.
إخلاء مسؤولية:
The performance figures quoted are not a guarantee of future performance.
الأسئلة الشائعة
لماذا وافقت الولايات المتحدة على تصدير شريحة H200 من Nvidia إلى الصين؟
هل ستؤثر رسوم الـ25% من الإيرادات على ربحية Nvidia؟
لماذا تسعى الشركات الصينية للحصول على رقائق H200 بهذه السرعة؟
ما مدى قوة الطلب الأساسي على الذكاء الاصطناعي لدى Nvidia؟
هل تواجه Nvidia خطر التنظيمات المتزايدة؟


